The conflict in the Middle East is intensifying as Yemen's Houthi forces step up attacks on Saudi Arabian infrastructure and Yemeni government positions, increasing risks to oil production and energy supplies. Disruptions to energy deliveries have pushed European benchmark natural gas prices above €85 per megawatt-hour, while EU gas storage facilities are currently around 74.5% full, significantly below the approximately 83.0% typically recorded during this period. In Germany, one of Europe's largest energy consumers, underground storage facilities are only about 61.0% full, well below the historical seasonal average of around 77.0%. These developments continue to create uncertainty for German companies, particularly energy-intensive manufacturers, as also discussed in our previous DAX 40 forecast.
In addition, the stock market remains under pressure from the latest macroeconomic data, which broadly confirmed analysts' expectations. In September, the eurozone Consumer Price Index increased from 0.4% to 0.6% month-on-month and from 3.2% to 3.8% year-on-year. Meanwhile, the core indicator, which excludes energy, food, alcohol and tobacco, remained at 0.2% on a monthly basis and accelerated from 2.4% to 2.5% annually. As a result, the non-seasonally adjusted Harmonised Index of Consumer Prices (HICP) increased from 103.69 to 104.31 points, reinforcing concerns that the European Central Bank (ECB) may need to tighten monetary policy further to bring inflation back toward its 2.0% target.
Meanwhile, German government bond yields have been declining recently, providing some support to equity valuations. The benchmark 10-year Bund yield is trading near 3.410%, compared with 3.471% earlier, while the yield on long-term 20-year bonds has decreased from 3.820% to 3.765%. The 30-year government bond yield has also retreated to approximately 3.787%, down from 3.828% in the previous trading sessions.
Among the leading gainers in the previous session were Rheinmetall AG (+6.26%), BMW AG (+3.52%), Mercedes-Benz Group AG (+2.87%), Volkswagen AG Vz. (+2.78%) and Fresenius SE (+2.78%).
The largest declines were recorded by SAP SE (–1.01%), Continental AG (–0.34%), Infineon Technologies AG (–0.15%), MTU Aero Engines AG (–0.03%) and Siemens AG (–0.01%).
Support and resistance levels
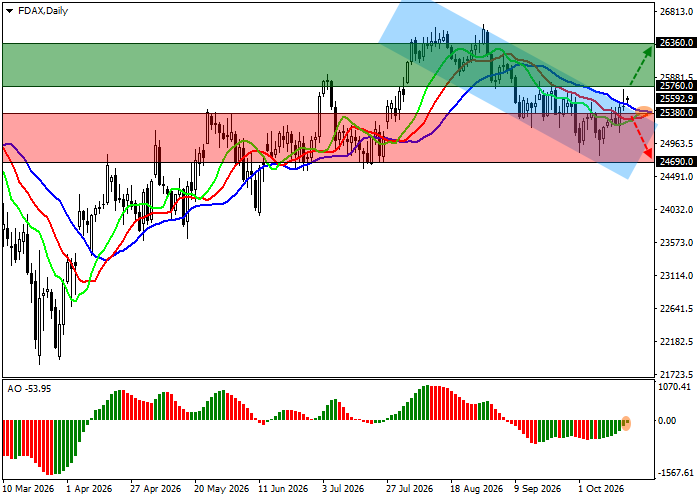
On the daily chart, the trading instrument is moving higher within a corrective trend, although it has retreated from the resistance line of the descending channel with boundaries at 25500.0–24700.0, which has been forming since the beginning of summer.
Technical indicators are preparing to generate a buy signal: the fast exponential moving averages (EMAs) of the Alligator indicator remain below the slow ones, while the Awesome Oscillator (AO) histogram is forming rising bars in negative territory.
Support levels: 25380.0, 24690.0.
Resistance levels: 25780.0, 26360.0.
DAX 40 Trading Scenarios and Index Forecast
Long positions may be opened after the price rises and consolidates above 25780.0, with a target at 26360.0. Stop-loss: 25300.0. Estimated implementation period: 7 days or more.
Short positions may be opened after the price declines and consolidates below 25380.0, with a target at 24690.0. Stop-loss: 25600.0.
Scenario
| Timeframe | Weekly |
| Recommendation | BUY STOP |
| Entry Point | 25780.0 |
| Take Profit | 26360.0 |
| Stop Loss | 25300.0 |
| Key Levels | 24690.0, 25380.0, 25780.0, 26360.0 |
Alternative Scenario
| Recommendation | SELL STOP |
| Entry Point | 25380.0 |
| Take Profit | 24690.0 |
| Stop Loss | 25600.0 |
| Key Levels | 24690.0, 25380.0, 25780.0, 26360.0 |
